

Top Tech Companies in Dublin (1,372)
.png)
The New Relic Intelligent Observability Platform helps businesses eliminate interruptions in digital experiences. New Relic is the only AI-strengthened platform to unify and pair telemetry data to provide clarity over your entire digital estate. We move your problem solving past proactive to predictive by processing the right data at the right time to maximize value and control costs. That’s why businesses...

New Relic's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is reported to have grown year over year in FY2023 to about $926 million, and the company later stated it had reached $1 billion in revenue. Together these points indicate increasing scale even if the precise current growth rate is not publicly disclosed.
Strong Market Position & Advantage: Industry evaluations place the company as a Leader in Gartner’s 2025 Observability Platforms and in IDC MarketScape assessments. Consistent positioning alongside major vendors signals durable competitive strength in its core market.
Market Expansion: The platform is described as serving more than 85,000 businesses worldwide, with expansions including a Dublin office and sharp increases in India headcount alongside investment in Japan. These moves indicate broader geographic reach and capacity to support growing demand.
Toast is the all-in-one platform built for restaurants of all sizes. Toast provides a single platform of software as a service (SaaS) products and financial technology solutions that give restaurants everything they need to run their business, including point of sale, payments, supplier management, digital ordering and delivery, marketing and loyalty, and team management. By serving as the restaurant operating...
Toast's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is increasing at a double‑digit pace, with Q2 2026 revenue of about $1.91B up year over year. Full-year 2025 revenue also rose meaningfully to roughly $6.15B from $4.96B the prior year, indicating momentum across periods.
Profitability: Profitability is improving, as Q2 2026 net income increased to about $154M and operating income to roughly $152M from the prior year’s quarter. Recurring gross profit from subscription and fintech reached approximately $585M, showing stronger unit economics alongside scale.
Market Expansion: Customer reach is widening, with roughly 9,500 net locations added in Q2 2026 and total locations around 180,000, both higher than a year earlier. The company is also extending into retail, enterprise, international markets, and AI-enabled products such as Toast IQ.
CSC is a global leader in providing business, legal, tax, and digital brand services to companies around the world. With more than 8,000 employees, CSC operates in more than 140 jurisdictions, delivering solutions that help businesses thrive. We pride ourselves on our client-focused approach, market-leading expertise, and unmatched global reach.
CSC's Top Stability & Growth Strengths
Market Expansion: Capabilities in more than 140 jurisdictions, the completed Intertrust integration, and investment in a larger Luxembourg office indicate sustained geographic scale-up. Acquisitions such as Intertrust and Eddystone broadened presence across Europe and Asia-Pacific while deepening local delivery.
Strong Market Position & Advantage: Adoption by a large majority of major enterprises and top global brands, plus category strength in registered agent and enterprise domain management, point to entrenched competitive standing. Independent industry recognition in capital-markets operations further underscores visibility in core niches.
Investor Backing & Capital Strength: Independent credit analyses reference mid‑single‑digit organic growth expectations, high profitability, and a large recurring-revenue base, supporting stable financing capacity. Deleveraging and an upgrade from a major ratings agency suggest solid access to capital and prudent balance‑sheet management.
Headquartered in Boston, Massachusetts, CarGurus is the #1 visited digital auto platform in the U.S. for shopping, buying, and selling new and used vehicles and an award-winning place to work. We give drivers and dealers the confidence to buy or sell cars exactly how they want: online, in-person, or a combination of both. Our culture fosters kindness, collaboration, and innovation,...

CarGurus's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising at a low-double-digit pace, with FY 2025 up 14% and Q1–Q2 2026 growing 15% and 13% year over year. Evidence indicates this marked a second consecutive year of double-digit annual growth with continued momentum into 2026.
Profitability: Profitability expanded faster than sales in 2025, with adjusted EBITDA up 25% and GAAP net income from continuing operations up 53%. This pattern points to improved operating leverage, even as quarterly results vary.
Market Expansion: International and dealer-network metrics show expansion, with total paying dealers up about 5% and international dealers up 11% year over year; international revenue rose 28% in Q2 2026. These gains suggest growth beyond the U.S. base and higher monetization per dealer.

Datadog (NASDAQ: DDOG) is a global SaaS business, delivering a rare combination of growth and profitability. We are on a mission to break down silos and solve complexity in the cloud age by enabling digital transformation, cloud migration, and infrastructure monitoring of our customers' entire technology stacks. Built by engineers, for engineers, Datadog is used by organizations of all sizes...

Datadog's Top Stability & Growth Strengths
Strong Revenue Growth: Recent financials show accelerating top-line expansion, with quarterly revenue surpassing the billion-dollar mark and full-year results climbing meaningfully. Momentum continued into 2026, reflecting broad demand across observability, security, and AI-related offerings.
Healthy Cash Flow: Operations are generating substantial operating and free cash flow alongside growth. This pattern persisted through mid-2026, indicating efficient scaling.
Strong Market Position & Advantage: Industry evaluations repeatedly place the company as a Leader in observability and digital experience monitoring, including top positioning for execution. Recognition such as Customers’ Choice and multi-product leadership suggests deep adoption and competitive strength.
Optum, part of the UnitedHealth Group family of businesses, is a global organization that delivers care, aided by technology to help millions of people live healthier lives. The work you do with our team will directly improve health outcomes by connecting people with the care, pharmacy benefits, data and resources they need to feel their best. Here, you will find...

Optum's Top Stability & Growth Strengths
Profitability: Operating earnings and margins improved notably in 2026, with Q3 operating earnings up sharply year over year and the operating margin rising to 5.6%. Feedback suggests earnings resilience is being supported by operational changes and a shifting business mix.
Strong Revenue Growth: Reported annual revenue expanded from $226.6B in 2023 to $270.6B in 2025, including roughly 12% growth in 2024 and 7% in 2025. This establishes a robust multi‑year revenue trajectory even as recent growth rates have moderated.
Cost & Operational Efficiency: Cost controls and operational improvements are described as lifting earnings despite lower revenue in 2026. Optum Health’s operating earnings rose from $41M to $735M year over year while serving fewer value‑based patients, indicating stronger execution.
Together, we turn ambition into action. For more than three decades, Citadel has captured undiscovered market opportunities in markets around the world by empowering extraordinary people to pursue their best and boldest ideas. We strive to identify the highest and best uses of capital to generate superior long-term returns for the world’s preeminent public and private institutions.
Citadel's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Investment capital is reported at approximately $77 billion as of October 1, 2026, and assets rose from $26 billion in 2015 to $67 billion by 2025. These figures point to substantial scale and a sustained ability to attract and retain capital.
Strong Hiring & Retention: Employee headcount at Citadel Advisors increased from 3,153 in 2024 to 3,284 in 2025. This pattern indicates active workforce expansion to support growing operations.
Market Expansion: The firm is exploring new opportunities, including discussions to acquire U.S. oil‑production assets, and plans to add Dubai as a new location. These moves signal continued broadening of its geographic and business footprint.
.png)
We bring people together around the things they love and turn their passions into their livelihood.

Whatnot's Top Stability & Growth Strengths
Strong Revenue Growth: Marketplace sales are described as surpassing $8B in 2025 and more than doubling from 2024, with first-half 2026 reportedly already exceeding all of 2025. Independent estimates also point to revenue scaling toward $1B in 2025, reinforcing commercial momentum.
Investor Backing & Capital Strength: Funding includes a $545M Series G at a reported $20B valuation, a substantial step up from the prior round. This signals deep capital access to fuel expansion and operations.
Market Expansion: Operations and hiring span hubs across the U.S. and Europe, while the platform added dozens of new categories and crossed one billion orders. These moves indicate broadening geographic reach and category depth.
Notion is a collaborative AI workspace. Teams use it to store knowledge, run projects, take meeting notes, and build AI workflows — all in one place, so AI always has the context it needs to be useful. We're building the layer where AI stops being a chat window and starts being part of how work gets done. Knowledge, decisions, and action...
Notion's Top Stability & Growth Strengths
Strong Revenue Growth: Available reporting indicates ARR exceeded $600M by late 2025 and was estimated near $865M by mid-2026, pointing to rapid expansion of the subscription business. Company commentary notes growth acceleration in 2025 alongside higher-value plans and usage-based additions tied to AI.
Innovation-Driven Growth: Evidence suggests AI adoption is a major revenue driver, with a rising share of ARR linked to AI-enabled customers and swift uptake of new AI offerings such as agents. These capabilities appear to be prompting upgrades to premium tiers and expanding monetization beyond core workspace features.
Investor Backing & Capital Strength: An employee share tender at an $11B valuation with participation from existing and new investors indicates continued access to capital and confidence in the trajectory. Reports of cash-flow positivity further underscore financial resilience.

Citadel Securities is a technology-driven, next-generation global market maker. We provide institutional and retail investors with world-class liquidity, competitive pricing and seamless front-to-back execution in a broad array of financial products. Our teams of engineers, traders and researchers harness leading-edge quantitative research and the accelerating power of compute, machine learning and AI to power our analytics and tackle the market’s...
Citadel Securities's Top Stability & Growth Strengths
Strong Revenue Growth: Trading revenue reached a record ~$12.2B in 2025, up about 25% from 2024, with record Q1 and Q2 2026 results reinforcing the trajectory. EBITDA also rose to roughly $6.5B, indicating earnings expansion alongside top-line growth.
Market Expansion: International hiring across six Asian markets in 2026 and a new Amsterdam office for European equity options point to deepening global reach and regional leadership builds. Senior appointments in EMEA and efforts to let Asian clients trade large U.S. equity blocks further extend coverage.
Product Line Growth: Launches in high-touch institutional equities and expansion in corporate bonds and fixed income broaden services beyond electronic market making. A venture tied to equity research (with Wolfe Research) adds new institutional capabilities and diversifies the offering.
Squarespace is a design-driven platform helping entrepreneurs build brands and businesses online. We empower millions of customers in more than 200 countries and territories with all the tools they need to create an online presence, build an audience, monetize, and scale their business.
Squarespace's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as having surpassed the $1B mark with continued year-over-year increases into 2024. Evidence indicates momentum persisted through mid-2024, including higher run-rate revenue and rising bookings.
Product Line Growth: The platform broadened from websites into commerce, payments, financing, and AI-powered tools. Announcements in 2025–2026 indicate ongoing investment to deepen functionality for entrepreneurs and sellers.
Market Expansion: The absorption of Google Domains’ assets and millions of additional domains materially widened its funnel and recurring-services footprint. International investments, such as expanded operations in Ireland, further point to geographic scaling.

About Coursera: Coursera was launched in 2012 by Andrew Ng and Daphne Koller with a mission to provide universal access to world-class learning. Coursera partners with leading university and industry partners to offer a broad catalog of content and credentials, including courses, Specializations, Professional Certificates, and degrees. Coursera’s platform innovations — including AI-powered personalized guide and features, like Role Play and...
Coursera + Udemy 's Top Stability & Growth Strengths
Strong Market Position & Advantage: Strong Market Position & Advantage: Scale is described as more than 290–300 million learners and roughly 18,000 enterprise customers after the May 2026 combination, indicating extensive reach across consumer and enterprise learning. The combined catalog spans university-backed credentials and a large instructor marketplace, supporting broad coverage of professional skills and AI-focused training.
Cost & Operational Efficiency: Cost & Operational Efficiency: Guidance points to approximately $115 million in annual cost synergies within 24 months of closing and an adjusted EBITDA margin target of about 14% for 2026. Udemy’s return to positive GAAP net income in 2025 further indicates an improving profitability trajectory for the combined business.
Innovation-Driven Growth: Innovation-Driven Growth: AI-related learning is expanding rapidly, with Udemy reporting 120% growth in AI course enrollments and Coursera citing a 33% increase in micro-credential enrollments. Subscription-led offerings and professional certificates are highlighted as key drivers of engagement and recurring revenue.
At Rapid7, our vision is to create a secure digital world for our customers, our industry, and our communities. We do this by harnessing our collective expertise and passion to challenge what’s possible and drive extraordinary impact. We’re building a dynamic and collaborative workplace where new ideas are welcome. Protecting 11,000+ customers against bad actors and threats means we’re continuing...
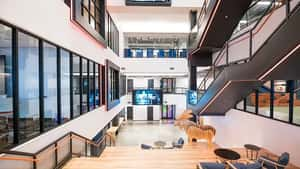
Rapid7's Top Stability & Growth Strengths
Profitability: Operating and net income remained positive even as revenue softened in recent quarters. This indicates an earnings base that is holding up during a period of slower demand.
Healthy Cash Flow: Free cash flow stayed positive with meaningful generation quarter to quarter, and guidance points to continued cash production. Liquidity is reinforced by a sizable balance of cash, cash equivalents, and government securities.
Future-Ready Strategy: Management is concentrating investment on the Command Platform, detection and response, exposure management, and AI-enabled security operations. This refocus aims to position the portfolio for a return to growth once the transition progresses.

Workhuman® is helping companies meet today’s biggest human capital challenges - including unprecedented turnover, employee engagement, hybrid work environments, and DE&I - through the Workhuman Cloud®, a secure SaaS platform that provides the industry’s best-in-class Social Recognition® solution. Co-Headquartered in Dublin, Ireland, and Framingham, Massachusetts, USA, Workhuman has been pioneering the human workplace to improve the employee experience at work,...

Workhuman's Top Stability & Growth Strengths
Profitability: Profitability is described as sustained for more than 15 years, with reports of over $100 million in annual operating profit alongside continued investment in AI. This points to durable financial strength that supports ongoing growth initiatives.
Market Expansion: Platform reach reportedly increased to 8 million users across 180+ countries, with more than 100 million recognition moments processed. This expanding global footprint indicates continued adoption and usage at enterprise scale.
Innovation-Driven Growth: The offering is extending beyond recognition into AI-powered workforce intelligence that surfaces insights on skills, collaboration, leadership, and culture. These advances can deepen value for existing customers and open additional growth pathways.
Geneva Trading LLC is a leading proprietary trading firm with a history of consistent success in the listed derivatives markets. Over the past 20 years, we’ve grown significant capital, developed proven technology, and maintained an appetite for diversified trading strategies. We foster innovation and look for people who can solve complex problems that drive immediate results. We've built a culture of...
Geneva Trading's Top Stability & Growth Strengths
Market Expansion: Feedback suggests the company has expanded its geographic footprint by opening a London office to build an energy-trading team and broaden participation in oil markets. Hiring across Chicago, Dublin, and London indicates active development of international operations.
Innovation-Driven Growth: Feedback suggests ongoing investment in trading technology, data and analytics, automation, and proprietary infrastructure to scale capabilities. Open roles in data engineering, C++ development, and platform engineering support the interpretation of continued technology-led expansion.
Diversified Revenue Streams: Feedback suggests activity across energy, fixed income, agriculture, FX, metals, environmental products, equity indices, and digital assets. This breadth provides multiple avenues for expanding trading activity and reduces reliance on a single market segment.

Pluralsight provides the only learning platform dedicated to accelerating the technology skills and capabilities of today’s tech workforce. Thousands of companies, government organizations, and individuals around the world rely on Pluralsight to support critical technology skill development in areas that are crucial to innovation, including artificial intelligence, cloud computing, cybersecurity, software development, and machine learning. Pluralsight offers highly curated content...

Pluralsight's Top Stability & Growth Strengths
Product Line Growth: New AI-focused launches in 2026—AI Ready, Cloud Ready, SecureReady, and AI Academy—indicate an active expansion of enterprise offerings. These moves point to efforts to capture demand in AI, cloud, and cybersecurity.
Investor Backing & Capital Strength: The August 2024 recapitalization reduced debt and provided more than $200 million to support growth initiatives. This capital injection signals renewed financial capacity to fund product and go-to-market investments.
Strong Market Position & Advantage: Independent analyst evaluations (Forrester and IDC) naming the company a Leader, alongside a sizable enterprise footprint reported at over 22,000 organizations with strong Fortune 500 reach, reflect an entrenched presence with enterprise buyers. These markers suggest the brand remains competitively positioned despite recent turbulence.
Headquartered in New York City, Take-Two Interactive Software, Inc. is a leading developer, publisher, and marketer of interactive entertainment for consumers around the globe. We develop and publish products principally through Rockstar Games, 2K, and Zynga. Our strategy is to create hit entertainment experiences, delivered on every platform relevant to our audience through a variety of sound business models. Our...
Take-Two Interactive Software's Top Stability & Growth Strengths
Strong Revenue Growth: Annual revenue and net bookings rose materially in FY2026, and guidance points to a further step-up in FY2027. The company highlights a sizable year-over-year increase in revenue and a higher bookings outlook tied to its pipeline.
Diversified Revenue Streams: Recurring consumer spending makes up a large share of results and mobile contributes meaningfully alongside console and PC franchises. This mix across Rockstar, 2K, and Zynga supports ongoing monetization between major releases.
Future-Ready Strategy: A defined pipeline anchored by the scheduled Grand Theft Auto VI launch and reaffirmed FY2027 bookings guidance signals preparation for the next growth phase. Management’s outlook ties expected expansion to both the new release and continued performance from sports and mobile titles.
Zynga was founded in 2007 with the vision that play would become one of the core activities on the Internet. We pioneered social games with the belief that if we could make games simple, accessible and social the world would start playing. We are excited that games have grown to become the second most popular activity by time spent, even...
Zynga's Top Stability & Growth Strengths
Strong Revenue Growth: Financial disclosures indicate mobile net bookings increased over the latest full fiscal year, alongside a notable rise in total company revenue and bookings, signaling momentum in the portfolio Zynga powers.
Strong Market Position & Advantage: Established franchises such as Toon Blast, Match Factory!, Words With Friends, and Zynga Poker are highlighted as major contributors, with multiple titles posting record or significant gains that reflect durable competitive standing.
Investor Backing & Capital Strength: Operating as a core label within Take-Two provides structural and financial support, enabling record direct-to-consumer performance and a continuing pipeline of mobile titles.
It's simple, at DraftKings, we believe life is more fun when you're in on the action. For that reason, we’re committed to responsibly creating the world’s favorite games and betting experiences. We’re developing the most innovative and entertaining real money products and offers; to forever transform how people experience sports; to be a fully vertically integrated sports betting operator. It's...

DraftKings's Top Stability & Growth Strengths
Strong Revenue Growth: Annual revenue rose from $3.67B in 2023 to $6.05B in 2025, and management guides to $6.5–$6.9B for 2026. This multi-year trajectory signals substantial top-line expansion despite quarterly volatility.
Market Expansion: The sportsbook operates in 30 states, Washington, D.C., Puerto Rico, and parts of Canada. Broader geographic access supports continued user and wagering growth.
Diversified Revenue Streams: Sportsbook, iGaming, and the newer Predictions offering provide multiple growth avenues. iGaming revenue grew 7.5% year over year in Q2 2026, while Predictions launched in December 2025 as another channel.

CWAN was founded on a simple belief: investment professionals deserve modern technology that actually works for them. Not legacy systems that slow them down. Not fragmented data that creates confusion. But one comprehensive platform that gives you complete visibility and crystal-clear insights. The result? Investment management that works as seamlessly as your investment strategy. Since our founding in 2004, CWAN has been...

Clearwater Analytics (CWAN)'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose sharply, with full-year 2025 reaching $731.4 million and Q1 2026 at $221.2 million, well above prior periods. Annualized recurring revenue also increased to $872 million, indicating momentum beyond a single quarter.
Customer Loyalty & Retention: Customer metrics show very high gross retention and positive net expansion in late 2025 and Q1 2026, indicating clients are staying and broadening their use of the platform. This points to growth from the installed base alongside new wins.
Profitability: Adjusted profitability improved as Q1 2026 adjusted EBITDA increased materially to $77.4 million. This suggests operating leverage alongside rapid top-line expansion.



