

Top Software Companies in Dublin (466)
.png)
Klaviyo (NYSE: KVYO) is the B2C CRM. Powered by its built-in data platform and AI, Klaviyo combines marketing automation, analytics, and customer service into one unified solution, making it easy for businesses to know their customers and grow faster. Klaviyo (CLAY-vee-oh) helps over 183,000 brands like Mattel, Glossier, Daily Harvest, and Liquid Death deliver 1:1 experiences at scale, improve efficiency,...
Klaviyo's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has scaled to over $1.2B with continued double-digit quarterly increases and an outlook nearing $1.5B, indicating sustained momentum. Guidance increases reinforce the trajectory of ongoing top-line expansion.
Market Expansion: International revenue is growing faster than the overall business and now represents a significant share of total revenue, with customers across more than 100 countries. The customer base surpassing 205,000 underscores broader geographic reach and upmarket penetration.
Customer Loyalty & Retention: Net revenue retention remains above 100%, suggesting existing customers are expanding spend through cross-selling and wider platform adoption. Larger-account cohorts are growing rapidly, including rising counts of $50K+ and $1M+ ARR customers.
Block, Inc. is a global technology company with a focus on financial services. Made up of Square, Cash App, Afterpay, TIDAL, Bitkey, and Proto, Block, Inc. builds technology to increase access to the global economy. Each of our brands unlocks different aspects of the economy for more people. Square makes commerce and financial services accessible to sellers. Cash App is the...
Block's Top Stability & Growth Strengths
Profitability: Operating profitability is strengthening, with Q2 2026 delivering a 27% adjusted operating margin and 65% growth in adjusted diluted EPS. For 2025, operating income also rose to $1.7B, highlighting improved earnings leverage.
Resilient & Sustainable Growth: Gross profit increased every year from 2021 to 2025 and accelerated 25% year over year in Q2 2026. Management raised its 2026 gross-profit outlook to $12.51B (about 21% growth), reinforcing a multi-period expansion trend.
Cost & Operational Efficiency: Efficiency measures and AI-driven execution are associated with faster product delivery and improved profitability. Workforce streamlining and operating leverage supported margin expansion alongside growth in both Cash App and Square.
Skillsoft (NYSE: SKIL) is a global leader in AI-native skills management for the human + AI era. By unifying learning, real-time skills intelligence, and workforce insights, Skillsoft helps enterprises build their Skillforce™ — humans and AI working together to drive measurable business outcomes. Through personalized, interactive learning across leadership, technology, and compliance, Skillsoft enables organizations to close critical skill gaps...

Skillsoft's Top Stability & Growth Strengths
Profitability: Adjusted EBITDA and margins improved even as sales contracted, and full-year adjusted EBITDA guidance was maintained despite a reduced revenue outlook. This points to better earnings execution and cost discipline.
Innovation-Driven Growth: AI-enabled offerings such as CAISY, AI Coach, and LX Design Studio show rising adoption and engagement. These signs indicate momentum in AI-powered skills development within the enterprise base.
Future-Ready Strategy: The company is refocusing on an AI-native skills management platform and core enterprise learning following the sale of Global Knowledge. This sharper portfolio focus suggests a strategic shift toward higher-potential, software-led growth.
Monte Carlo is the agent trust platform that unifies data and agent observability to monitor, troubleshoot, and improve production AI systems. As enterprises prepare to deploy thousands of agents across business-critical use cases, Monte Carlo provides the reliability infrastructure to support them along this AI transformation, from human-guided agents to fully autonomous operations. Founded 2019. Backed by leading investors. Trusted...

Monte Carlo's Top Stability & Growth Strengths
Investor Backing & Capital Strength: The company secured a $135 million Series D in 2022, bringing total funding to $236 million and a reported billion-plus valuation. This capital base supports continued investment in product and market initiatives.
Strong Market Position & Advantage: The company reports more than 400 enterprise customers, including PepsiCo, Cisco, Nasdaq, Roche, and The New York Times. This breadth points to meaningful enterprise adoption and commercial scale.
Product Line Growth: The platform has expanded from data observability into AI reliability and agent observability, monitoring AI agents in production alongside underlying data pipelines. Company-reported usage metrics—such as 10 million tables monitored and 1,000 incidents resolved daily—indicate a growing product footprint.
.png)
Expedia Group, Inc. is the global travel marketplace with one purpose: to help travelers explore the world, one journey at a time. Expedia Group™ connects travelers, partners, and advertisers through its trusted brands, leading technology, and rich first-party data, delivering predictive, personalized experiences that shape the future of travel. Expedia Group’s ecosystem includes three flagship consumer brands – Expedia®, Hotels.com®, and...

Expedia Group's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased 8% in 2025 and accelerated to 14% year over year in Q2 2026, with management raising full‑year revenue guidance to $16.05–$16.22 billion. Gross bookings also rose 8% in 2025 and 12% in Q2 2026, indicating expanding underlying travel activity.
Profitability: Operating income grew 42% in 2025 and surged 65% in Q2 2026, while GAAP net income jumped 166% in that quarter. Adjusted EBITDA rose 19% in 2025 and 23% in Q2 2026, suggesting improved operating leverage alongside growth.
Diversified Revenue Streams: Both distribution channels are contributing, with Q2 2026 B2B gross bookings up 21% (B2B revenue up 23%) and B2C gross bookings up 8%. Lodging remained a key driver as lodging gross bookings rose 11% and booked room nights increased 6% in Q2 2026.
Citadel Securities is a technology-driven, next-generation global market maker. We provide institutional and retail investors with world-class liquidity, competitive pricing and seamless front-to-back execution in a broad array of financial products. Our teams of engineers, traders and researchers harness leading-edge quantitative research and the accelerating power of compute, machine learning and AI to power our analytics and tackle the market’s...
Citadel Securities's Top Stability & Growth Strengths
Strong Revenue Growth: Trading revenue reached a record ~$12.2B in 2025, up about 25% from 2024, with record Q1 and Q2 2026 results reinforcing the trajectory. EBITDA also rose to roughly $6.5B, indicating earnings expansion alongside top-line growth.
Market Expansion: International hiring across six Asian markets in 2026 and a new Amsterdam office for European equity options point to deepening global reach and regional leadership builds. Senior appointments in EMEA and efforts to let Asian clients trade large U.S. equity blocks further extend coverage.
Product Line Growth: Launches in high-touch institutional equities and expansion in corporate bonds and fixed income broaden services beyond electronic market making. A venture tied to equity research (with Wolfe Research) adds new institutional capabilities and diversifies the offering.
.png)
Since we opened our doors in 2009, the world of commerce has evolved immensely, and so has Square. After enabling anyone to take payments and never miss a sale, we saw sellers stymied by disparate, outmoded products and tools that wouldn’t work together. So we expanded into software and started building integrated, omnichannel solutions – to help sellers sell online, manage...

Square's Top Stability & Growth Strengths
Strong Revenue Growth: Square’s segment revenue increased 10% in 2025 and rose 16% year over year in Q2 2026, pointing to renewed topline momentum. These gains accompany rising seller activity and broader ecosystem adoption.
Profitability: Gross profit reached about $1.16 billion in Q2 2026, up 13% year over year, after a 9% increase for full-year 2025. The trend indicates improving economic contribution from processing, software, and financial services.
Market Expansion: International GPV grew 28% year over year in Q2 2026 while U.S. GPV rose 10%, alongside traction with larger merchants and vertical solutions such as restaurants and banking. These patterns suggest widening geographic and segment reach.
At Rapid7, our vision is to create a secure digital world for our customers, our industry, and our communities. We do this by harnessing our collective expertise and passion to challenge what’s possible and drive extraordinary impact. We’re building a dynamic and collaborative workplace where new ideas are welcome. Protecting 11,000+ customers against bad actors and threats means we’re continuing...
Rapid7's Top Stability & Growth Strengths
Profitability: Operating and net income remained positive even as revenue softened in recent quarters. This indicates an earnings base that is holding up during a period of slower demand.
Healthy Cash Flow: Free cash flow stayed positive with meaningful generation quarter to quarter, and guidance points to continued cash production. Liquidity is reinforced by a sizable balance of cash, cash equivalents, and government securities.
Future-Ready Strategy: Management is concentrating investment on the Command Platform, detection and response, exposure management, and AI-enabled security operations. This refocus aims to position the portfolio for a return to growth once the transition progresses.
Dynatrace lets customers understand their business like never before, so they can see beyond the complexity, find and fix problems faster and automate manual tasks with Al — so they can focus on what truly matters: running their business.

Dynatrace's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is advancing at double-digit rates across multiple periods, with FY2026 revenue rising 19% to about $2.02B and fiscal Q1 FY2027 revenue up 16% to $555M. ARR also increased 17% in the latest quarter, reinforcing breadth of growth in a subscription model.
Healthy Cash Flow: Cash generation is robust, including approximately $529M in free cash flow for FY2026 and operating cash flow of roughly $306M in Q1 FY2027. These indicators suggest expansion is supported by solid liquidity rather than heavy cash burn.
Product Line Growth: Log management is scaling rapidly, with annualized consumption reaching about $200M in Q1 FY2027 and growing at more than 100% year over year. Investment in AI-powered operations and platform capabilities is extending the growth runway.

InterSystems builds the software that makes complex systems work—reliably, securely, and at scale. For more than 45 years, we’ve been the information engine behind some of the world’s most mission-critical applications in healthcare, government, and business. Our data management, integration, and analytics technologies help organizations connect disparate systems, turn data into insight, and deliver better outcomes. From enabling interoperable healthcare and...

InterSystems's Top Stability & Growth Strengths
Strong Hiring & Retention: Employee headcount is increasing over the 2023–2026 period, indicating ongoing hiring momentum. Feedback suggests workforce expansion is sustained even if the pace has moderated recently.
Market Expansion: A new Jakarta office was opened in 2026 to deepen engagement across Southeast Asia. Operations span dozens of offices in many countries, supporting customers in more than 80 countries.
Innovation-Driven Growth: New offerings such as the Data Studio AI Assistant and continued development of healthcare interoperability products point to active product investment. Feedback suggests AI and healthcare enhancements are a current strategic focus.
It's simple, at DraftKings, we believe life is more fun when you're in on the action. For that reason, we’re committed to responsibly creating the world’s favorite games and betting experiences. We’re developing the most innovative and entertaining real money products and offers; to forever transform how people experience sports; to be a fully vertically integrated sports betting operator. It's...

DraftKings's Top Stability & Growth Strengths
Strong Revenue Growth: Annual revenue rose from $3.67B in 2023 to $6.05B in 2025, and management guides to $6.5–$6.9B for 2026. This multi-year trajectory signals substantial top-line expansion despite quarterly volatility.
Market Expansion: The sportsbook operates in 30 states, Washington, D.C., Puerto Rico, and parts of Canada. Broader geographic access supports continued user and wagering growth.
Diversified Revenue Streams: Sportsbook, iGaming, and the newer Predictions offering provide multiple growth avenues. iGaming revenue grew 7.5% year over year in Q2 2026, while Predictions launched in December 2025 as another channel.
Notion is a collaborative AI workspace. Teams use it to store knowledge, run projects, take meeting notes, and build AI workflows — all in one place, so AI always has the context it needs to be useful. We're building the layer where AI stops being a chat window and starts being part of how work gets done. Knowledge, decisions, and action...
Notion's Top Stability & Growth Strengths
Strong Revenue Growth: Available reporting indicates ARR exceeded $600M by late 2025 and was estimated near $865M by mid-2026, pointing to rapid expansion of the subscription business. Company commentary notes growth acceleration in 2025 alongside higher-value plans and usage-based additions tied to AI.
Innovation-Driven Growth: Evidence suggests AI adoption is a major revenue driver, with a rising share of ARR linked to AI-enabled customers and swift uptake of new AI offerings such as agents. These capabilities appear to be prompting upgrades to premium tiers and expanding monetization beyond core workspace features.
Investor Backing & Capital Strength: An employee share tender at an $11B valuation with participation from existing and new investors indicates continued access to capital and confidence in the trajectory. Reports of cash-flow positivity further underscore financial resilience.
Optum, part of the UnitedHealth Group family of businesses, is a global organization that delivers care, aided by technology to help millions of people live healthier lives. The work you do with our team will directly improve health outcomes by connecting people with the care, pharmacy benefits, data and resources they need to feel their best. Here, you will find...

Optum's Top Stability & Growth Strengths
Profitability: Operating earnings and margins improved notably in 2026, with Q3 operating earnings up sharply year over year and the operating margin rising to 5.6%. Feedback suggests earnings resilience is being supported by operational changes and a shifting business mix.
Strong Revenue Growth: Reported annual revenue expanded from $226.6B in 2023 to $270.6B in 2025, including roughly 12% growth in 2024 and 7% in 2025. This establishes a robust multi‑year revenue trajectory even as recent growth rates have moderated.
Cost & Operational Efficiency: Cost controls and operational improvements are described as lifting earnings despite lower revenue in 2026. Optum Health’s operating earnings rose from $41M to $735M year over year while serving fewer value‑based patients, indicating stronger execution.
Qualtrics is trusted by thousands of the world’s best organizations to power exceptional customer and employee experiences that build deep human connections, increase customer loyalty, boost employee engagement, and drive business success. Our advanced AI and specialized Experience Agents™ allow businesses and governments to proactively interact with customers and employees in personalized ways across every channel and touchpoint, respond in-the-moment...
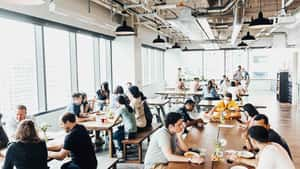
Qualtrics's Top Stability & Growth Strengths
Strong Revenue Growth: Historical 2022 results showed robust year-over-year expansion, and leadership later indicated the business was heading toward about $2 billion in revenue. These signals indicate meaningful scale and ongoing momentum.
Innovation-Driven Growth: AI product adoption and platform usage have surged since 2023, with a sizable share of customers upgrading to new AI capabilities. Company disclosures describe sharp increases in monthly active AI users and total interactions analyzed on the platform.
Market Expansion: Completion of the $6.75B Press Ganey Forsta acquisition broadens reach into healthcare experience data, relationships, and analytics. This materially expands the company’s footprint and opportunities for cross-sell.

CWAN was founded on a simple belief: investment professionals deserve modern technology that actually works for them. Not legacy systems that slow them down. Not fragmented data that creates confusion. But one comprehensive platform that gives you complete visibility and crystal-clear insights. The result? Investment management that works as seamlessly as your investment strategy. Since our founding in 2004, CWAN has been...

Clearwater Analytics (CWAN)'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose sharply, with full-year 2025 reaching $731.4 million and Q1 2026 at $221.2 million, well above prior periods. Annualized recurring revenue also increased to $872 million, indicating momentum beyond a single quarter.
Customer Loyalty & Retention: Customer metrics show very high gross retention and positive net expansion in late 2025 and Q1 2026, indicating clients are staying and broadening their use of the platform. This points to growth from the installed base alongside new wins.
Profitability: Adjusted profitability improved as Q1 2026 adjusted EBITDA increased materially to $77.4 million. This suggests operating leverage alongside rapid top-line expansion.
Sprout Social is a leading AI-powered social intelligence platform, built on the belief that All Business is Social℠. Powered by Trellis, Sprout’s proprietary AI agent, the platform transforms real-time social media signals into actionable insights that drive business forward. Consistently recognized as a top software by G2, Sprout enables brands to deliver smarter, faster business impact through a suite of...
Sprout Social's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Revenue continues to rise year over year, with recent quarters showing steady low–double-digit expansion and management guiding to continued growth in 2026. Feedback suggests the business is prioritizing balanced expansion over hypergrowth.
Cost & Operational Efficiency: Operating performance has improved, with GAAP losses narrowing and non-GAAP operating income and margins moving higher. Guidance points to a stronger exit margin by year-end 2026, indicating tighter cost control and operating leverage.
Diversified Customer Base: The company serves tens of thousands of customers across more than 100 countries, and the number of higher-ARR customers has increased. This breadth, alongside upmarket traction, supports ongoing expansion across segments.
We’re one of the world’s leading online gambling companies, revolutionizing the industry since 2000. Founded by Denise Coates CBE, we now employ over 10,000 people and serve over 120 million customers in 26 languages. We empower our employees to push boundaries and explore new ideas, cultivating a culture that celebrates and rewards creativity. This offers employees a wealth of...

bet365's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased by 9% to about £4.04 billion in the 52 weeks to March 2025. This points to continued top-line expansion despite heavier spending tied to new markets.
Market Expansion: A U.S. headquarters opened in Denver with plans for hundreds of roles and further state launches, alongside international entries in Brazil, Peru, and Serbia. The purchase of the Denver property for roughly $135 million underscores commitment to North American growth.
Strong Hiring & Retention: Average headcount rose from 6,085 in 2022 to 9,462 in 2025, and roles continue to be advertised across technology, trading, marketing, and customer service. Company materials cite a workforce of over 10,000, indicating substantial organizational scale.
Together, we turn ambition into action. For more than three decades, Citadel has captured undiscovered market opportunities in markets around the world by empowering extraordinary people to pursue their best and boldest ideas. We strive to identify the highest and best uses of capital to generate superior long-term returns for the world’s preeminent public and private institutions.
Citadel's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Investment capital is reported at approximately $77 billion as of October 1, 2026, and assets rose from $26 billion in 2015 to $67 billion by 2025. These figures point to substantial scale and a sustained ability to attract and retain capital.
Strong Hiring & Retention: Employee headcount at Citadel Advisors increased from 3,153 in 2024 to 3,284 in 2025. This pattern indicates active workforce expansion to support growing operations.
Market Expansion: The firm is exploring new opportunities, including discussions to acquire U.S. oil‑production assets, and plans to add Dubai as a new location. These moves signal continued broadening of its geographic and business footprint.
2K is headquartered in Novato, California and is a wholly owned label of Take-Two Interactive Software, Inc. (NASDAQ: TTWO). Founded in 2005, 2K Games is a global video game company, publishing titles developed by some of the most influential game development studios in the world. Our studios responsible for developing 2K’s portfolio of world-class games across multiple platforms, include Visual...
2K's Top Stability & Growth Strengths
Strong Revenue Growth: Parent-company revenue and net bookings increased in fiscal 2026, with NBA 2K identified among the largest contributors, and franchise revenue for NBA 2K rising materially year over year. NBA 2K26 unit sell-in also exceeded the prior title’s level, reinforcing momentum.
Product Line Growth: Multiple 2K releases were cited among leading contributors, including NBA 2K26 and WWE 2K26, while the active slate spans Civilization VII, Borderlands 4, and Mafia: The Old Country. This breadth indicates continued investment across several established franchises.
Customer Loyalty & Retention: Player engagement and recurrent consumer spending for NBA 2K increased meaningfully during fiscal 2026. Reported gains in daily active users alongside higher in-game spending point to durable participation within the ecosystem.
We're a global community of bold visionaries and resourceful doers who are shaping the future of Dropbox—and with it the future of work. Our Virtual First model combines the flexibility of a distributed workplace with the power of human connection, making space for both meaningful work and meaningful relationships. With our start-up mindset and enterprise-level opportunities, you can be who...

Dropbox's Top Stability & Growth Strengths
Healthy Cash Flow: Cash generation is described as substantial, with unlevered free cash flow of about $1.016B in 2025 and $283.5M in Q2 2026, indicating strong cash-producing ability despite modest top-line growth.
Profitability: Margins are portrayed as strong, with a 40.6% non-GAAP operating margin in 2025 and near 40% in Q2 2026, reflecting disciplined cost management and efficient operations.
Resilient & Sustainable Growth: Feedback suggests core revenue excluding FormSwift has returned to slight year-over-year growth and paying users have increased for several consecutive quarters, pointing to stabilization and incremental expansion.



